Research
My research develops statistical and computational methodology for complex, high-dimensional probability models, with an emphasis on Bayesian inference, graphical models, and Monte Carlo methods.
Short summary of selected recent projects:
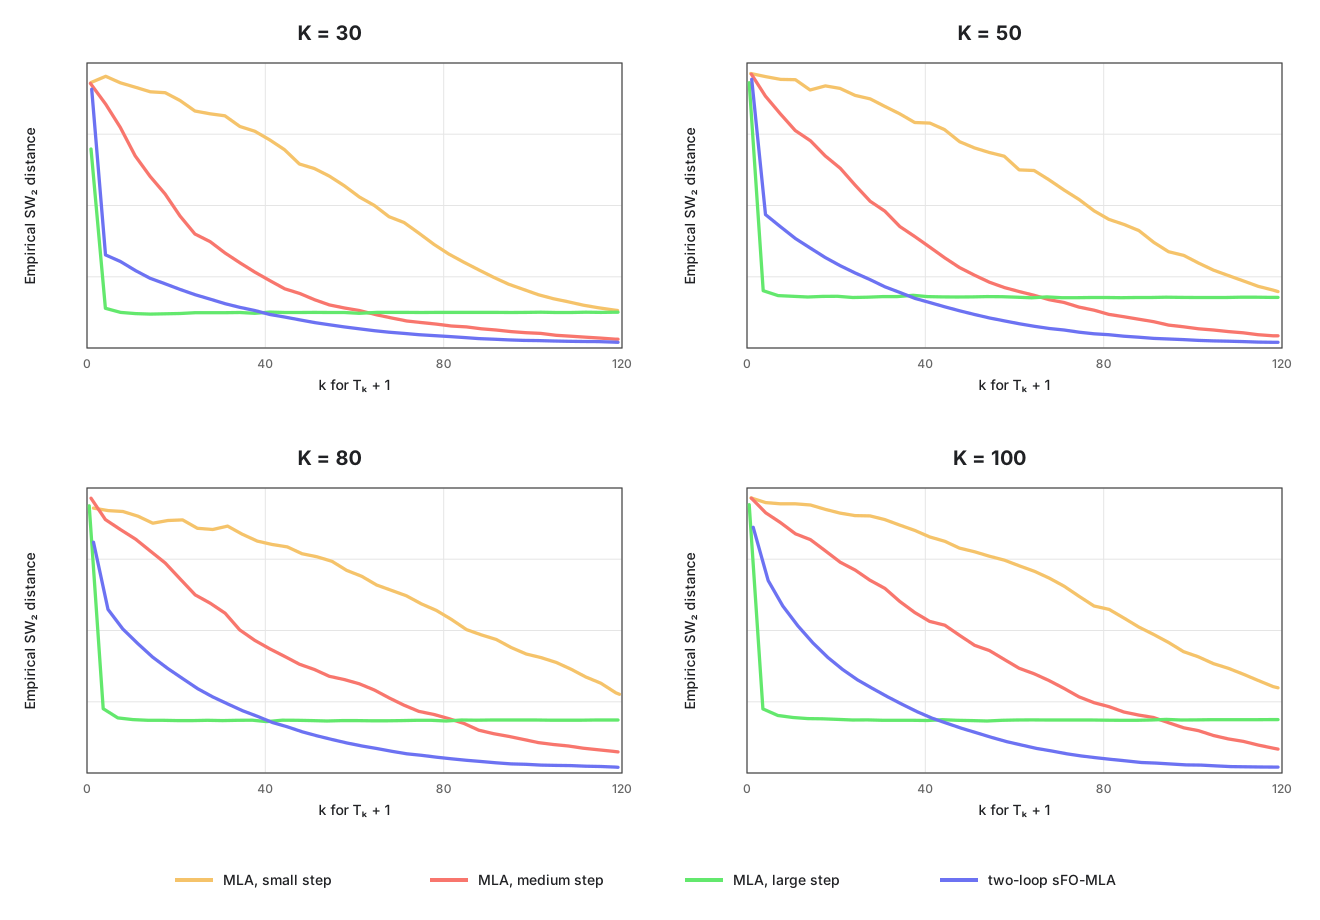
Stochastic Mirror Langevin Sampling
Stochastic first-order Mirror Langevin algorithms enable sampling from constrained distributions when gradients are available only through noisy estimates. A warm-started two-loop scheme progressively decreases the step size, allowing the sampler to move beyond the discretization error floor of fixed-step implementations while retaining efficient mixing.
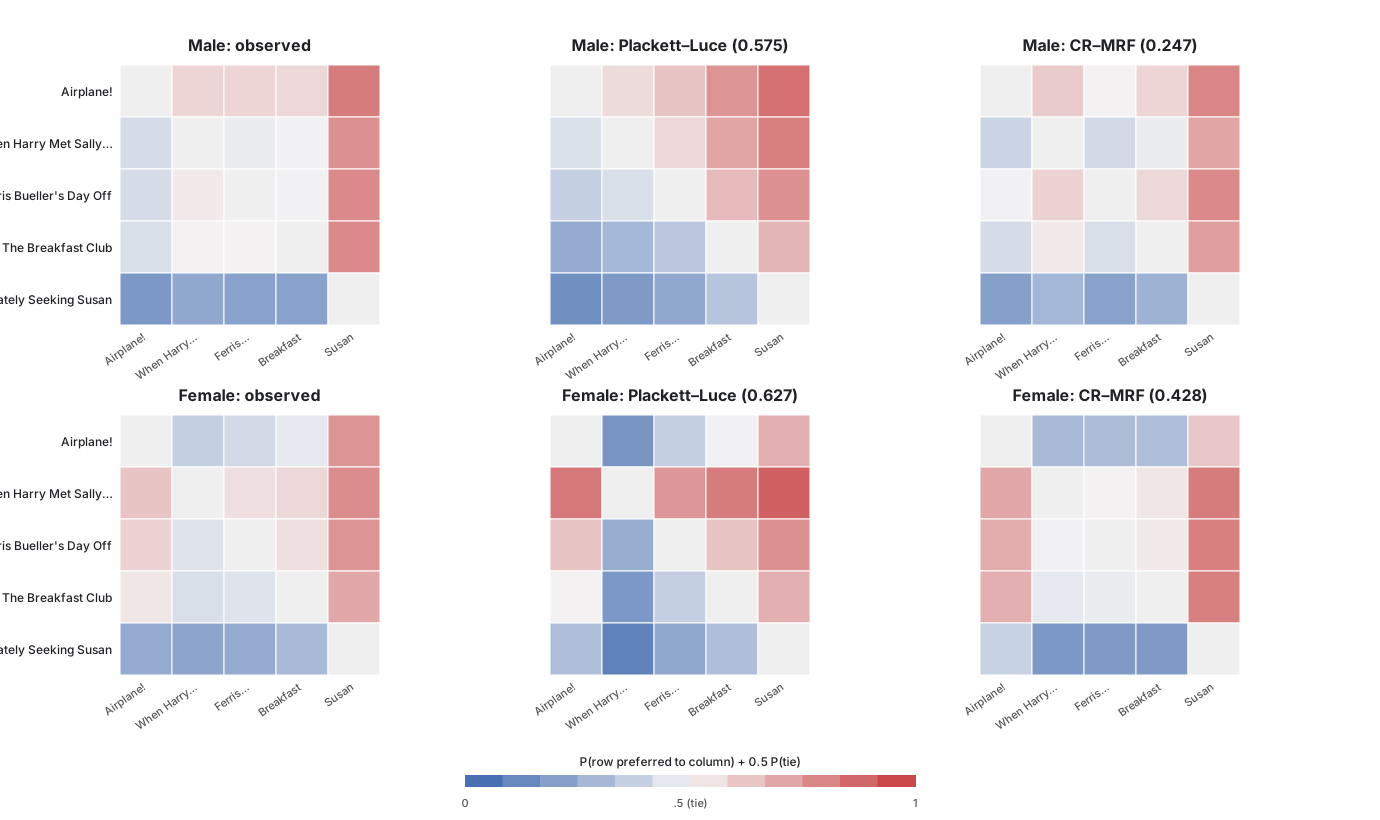
Covariate-Dependent Graphical Models for Ordinal Preferences
Covariate-dependent consecutive-ratio Markov random fields provide a joint model for multivariate ordinal preferences. The framework preserves the original ordinal ratings while allowing both marginal preference effects and dependence among items to vary with covariates, with direct connections to classical pairwise-comparison and ranking models.
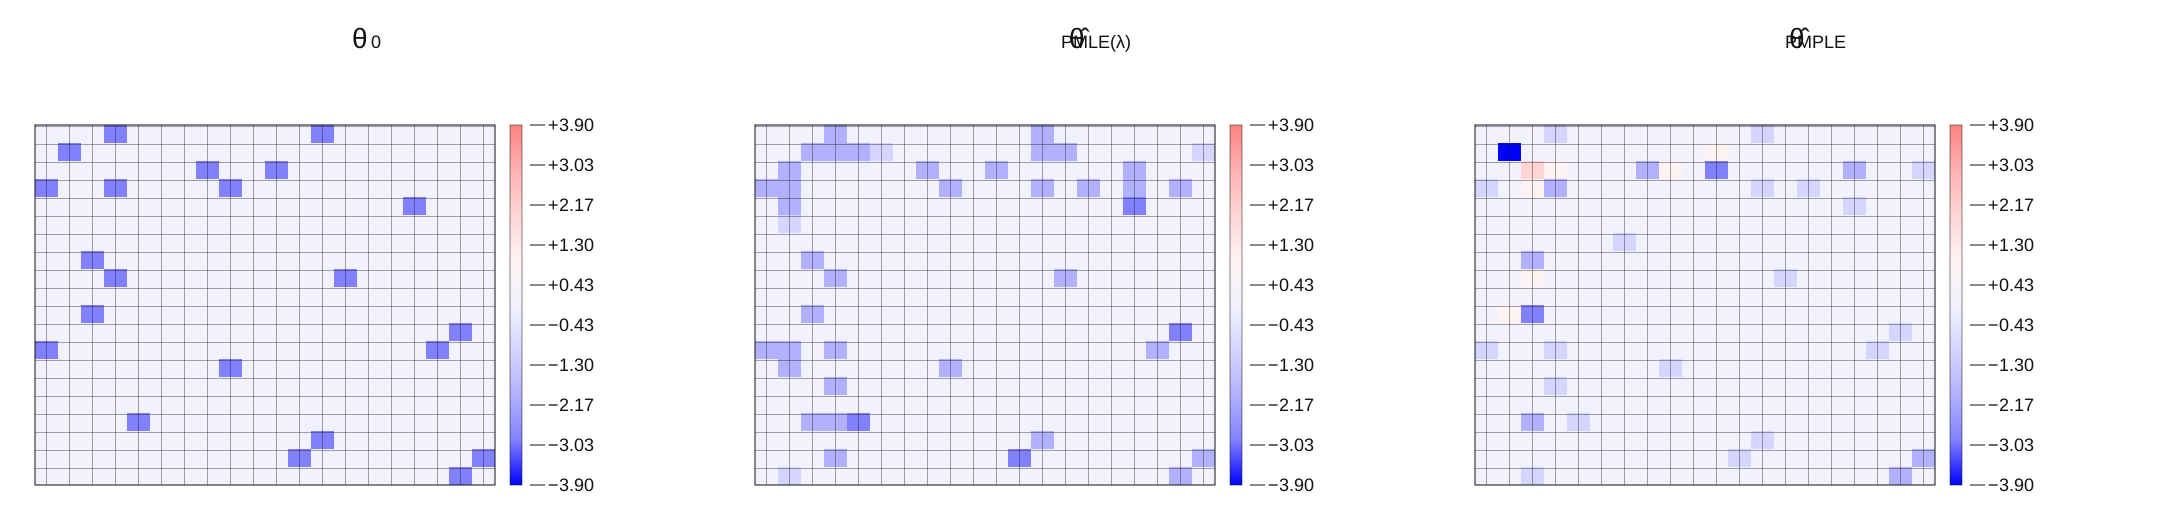
Likelihood-Based Inference for Intractable Graphical Models
Likelihood-based inference for exponential-family graphical models is made computationally feasible despite the presence of intractable normalizing constants. By exploiting the tractable independence model underlying the graphical model, the approach supports full maximum-likelihood and Bayesian inference and can improve parameter estimation and graph recovery relative to conventional pseudo-likelihood methods.


Orthogonal Bayesian Calibration
Posterior projection provides a Bayesian route to computer-model calibration under an orthogonality constraint on the discrepancy function. This construction addresses identifiability between calibration parameters and model discrepancy while allowing flexible nonparametric priors and extending naturally to multivariate physical systems.